
The artificial intelligence (AI) infrastructure boom has supercharged Nvidia and Micron Technology‘s growth in recent years, as both companies sell mission-critical chips deployed in AI data centers for model training and inference.
Not surprisingly, investments in Nvidia and Micron have been highly lucrative for investors. Importantly, both semiconductor stocks still have room for more upside, fueled by further growth in AI infrastructure investments.
However, there is one AI infrastructure stock that has failed to capitalize on this fast-growing space despite its impressive numbers. Shares of Oracle (ORCL +0.64%) are down 52% over the past year. But a closer look at the company’s latest quarterly report suggests investors may be underestimating its potential. Here’s why.

Image source: The Motley Fool.
Oracle’s incredible growth is going to send the stock on a bull run
Oracle released its fiscal 2027 first-quarter results (for the three months ended Aug. 31) on Sept. 10. The company’s revenue increased 30% year over year to a record $19.3 billion. Additionally, the company’s non-GAAP earnings per share rose 30% year over year to $1.92.

Today’s Change
(0.64%) $0.95
Current Price
$148.56
Key Data Points
Market Cap
$446BMarket cap calculated using publicly traded shares outstanding only. Does not include unlisted, private, or dual-class non-traded shares. Implied market cap may vary.
Day’s Range
$146.16 – $149.98
52wk Range
$114.50 – $329.50
Volume
22.4M
Avg Vol
33.3M
Gross Margin
61.93%
Dividend Yield
1.35%
Analysts would have settled for $1.75 in earnings per share. However, it seems that the company’s business model of asking customers to prepay for AI accelerator chips or to bring their own hardware is having a positive impact on its bottom line. Even Oracle’s revenue exceeded the $19.14 billion consensus estimate, suggesting that it is converting its backlog into revenue at a solid pace now.
The good news for Oracle investors is that its revenue backlog continues to improve. The company’s remaining performance obligation (RPO), which is the total value of unfulfilled contracts at the end of a quarter, increased by $209 billion from the year-ago quarter. The metric now stands at a massive $664 billion, paving the way for solid long-term growth in revenue and earnings.
Even better, Oracle notes that the conversion of RPO into revenue is poised to accelerate over the remainder of fiscal 2027. The company now expects to convert half of its RPO into revenue over the next three years, compared to the earlier estimate of 46%. So, Oracle is on track to generate $332 billion in revenue over the next three years, translating into an annual run rate of almost $111 billion.
That points to a significant improvement over Oracle’s fiscal 2026 revenue of $67.4 billion. What’s more, Oracle management’s comments indicate that the stronger jump in revenue will also give its bottom line a nice boost. CFO Hilary Maxson noted on the latest earnings call that the “new RPO will not impact our capex or revenues until fiscal 2028 or beyond.”
The company’s bring-your-own-hardware/prepayment business model is therefore bearing fruit. This is also evident from Oracle’s improving non-GAAP operating income, which increased 21% year over year in fiscal Q1 on a trailing-twelve-month basis. That was a significant improvement over the year-ago period’s growth rate of 8%.
As such, I won’t be surprised to see Oracle exceeding its guidance in fiscal 2027. The company anticipates a 34% year-over-year increase in revenue to $90 billion this fiscal year, while non-GAAP earnings are expected to increase by 18% to $8.10 per share. However, the fiscal Q1 performance clearly suggests that Oracle is on track to outperform that.
More importantly, Oracle’s conversion of backlog into revenue will send the stock significantly higher over the next three years.
Here’s how Oracle can become a multibagger
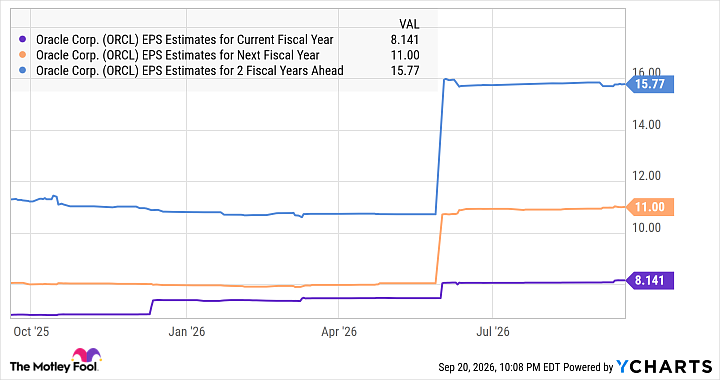
As Oracle’s capital expenses taper off and backlog conversion accelerates, its bottom-line growth will also pick up. This explains why analysts are expecting a substantial step-up in earnings growth over the next couple of fiscal years.
ORCL EPS Estimates for Current Fiscal Year data by YCharts
Oracle’s earnings growth rate could double in fiscal 2028, as evident from the chart above, followed by a 43% increase in fiscal 2029. Oracle trades at 18 times forward earnings, lower than the tech-laden Nasdaq-100 index’s forward earnings multiple of 24. A pick-up in earnings growth should be rewarded with a higher valuation.
Assuming Oracle trades at 30 times earnings after three years and its earnings per share reach $15.77 in fiscal 2029, the stock could jump to $473. That’s over 3x where Oracle stock is right now. So, savvy investors can consider buying this beaten-down stock right away and holding it for the long run, considering its healthy upside potential.